- Details
- Written by: Website Updates
- Category: About the OAG
- Hits: 18
The Performance Audit Branch audits the economy, efficiency and effectiveness with which the audited public entity uses its resources in carrying out its responsibilities. This type of audit is sometimes called a ‘value for money’ audit.
Find out more about the Performance Audit Branch (PAB)
- Details
- Written by: Website Updates
- Category: About the OAG
- Hits: 52
The Government Financial Audit Branch (GFAB) deals with financial statements audits, compliance audits and accounts and records audit on an annual basis for national accounts of the Solomon Islands Government (SIG).
Find out more about the Government Financial Audit Branch (GFAB)
- Details
- Written by: Website Updates
- Category: About the OAG
- Hits: 16
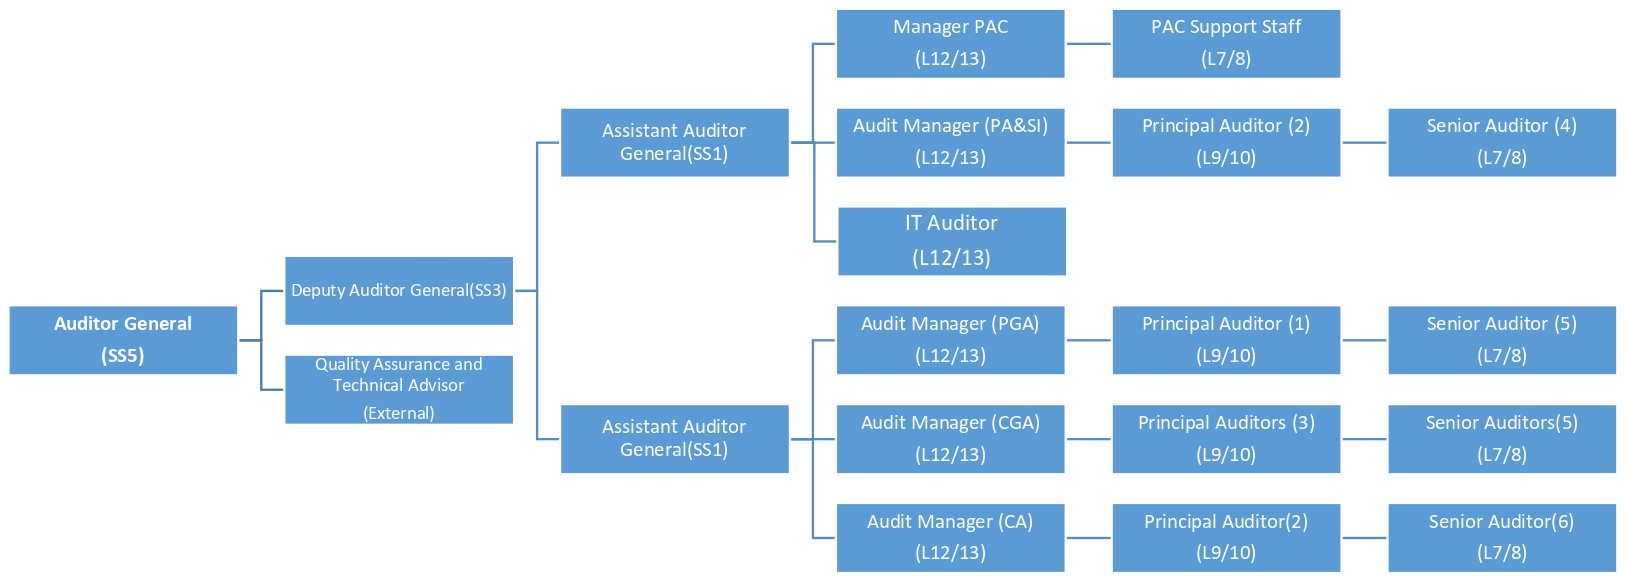
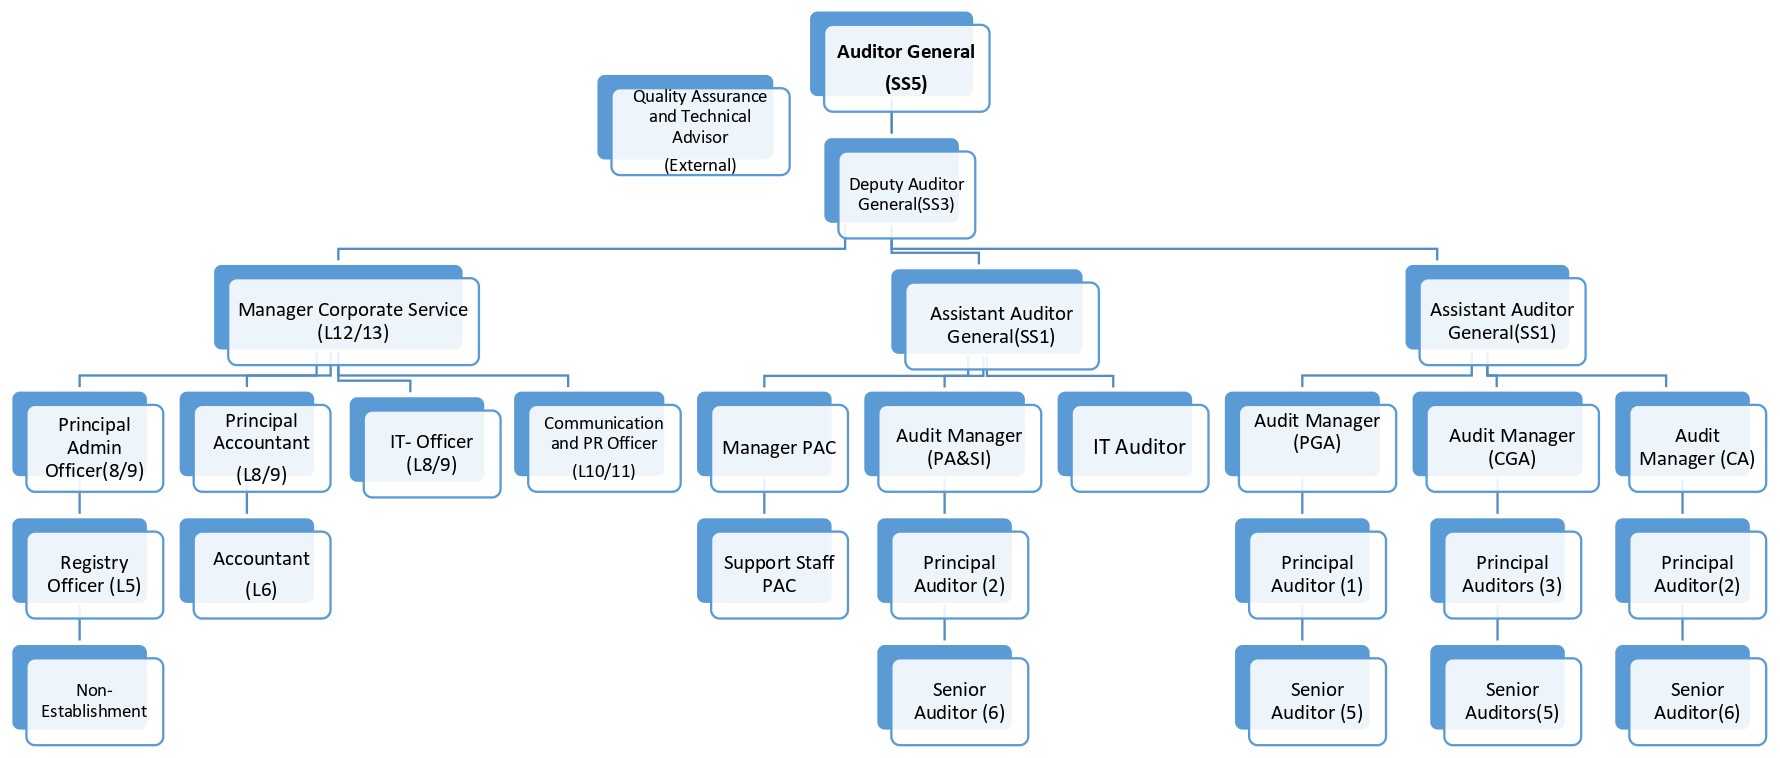
The Office of the Auditor General is made up of five Branches who work under the management and guidance of the Office’s Executives. The Executives include the Auditor General and the Deputy Auditor General.
Technical Structure
Complete Organisational Structure
- Details
- Written by: Website Updates
- Category: About the OAG
- Hits: 20
The Office of the Auditor General (OAG) has a number of goals that it aims to achieve. The OAG has set for itself a number of objectives to help it realise these goals. Each objective is tied to a strategy for implementation that are spelled out in the OAG’s pdfCorporate Plan 2022-2027(1.45 MB).
Objective 1: Fully Independent: This objective will require the OAG to have its own legislation, establishing a modern OAG with its own premises, budget and Scheme of Service for OAG staff. This objective will also help the OAG to actively participate in international organisations relevant to its work such as the Pacific Association of Supreme Audit Institutions (PASAI) and the International Organisation of Supreme Audit Institutions (INTOSAI).
Find out more about
Pacific Association of Supreme Audit Institutions (PASAI)
International Organisation of Supreme Audit Institutions (INTOSAI)
Objective 2: Effective Reporting: This objective will require the OAG to produce timely reports that are of high quality and which demonstrate accurate and comprehensive understanding of topics and issues. These reports must be easily understood by the OAG’s target audience and have the persuasion needed to draw support for the implementation of the recommendations of these reports. This objective will require the OAG to establish a close working relationship with its stakeholders including the Public Accounts Committee (PAC) and to engage in active awareness and public support programs.
Find out more about
The OAG and Effective Reporting
The OAG and the Public Accounts Committee (PAC)
Objective 3: Compliance with International Standards: This objective aims to ensure the OAG’s compliance with International Standards of Supreme Audit Institutions (ISSAI). These professional standards and best practice guidelines for public auditors such as the Auditor General are officially authorised and endorsed by the International Organisation of Supreme Audit Institutions (INTOSAI).
Find out more about
The OAG and Compliance and Standards
International Standards of Supreme Audit Institutions (ISSAI)
Objective 4: Professional Staff: This objective aims to develop the OAG’s staff to levels of international accreditation and professional standards that comply with the Solomon Islands Government’s Code of Conduct and International Standards of Supreme Audit Institutions (ISSAIs).
Objective 5: Efficient Management Support: This objective aims to develop effective Corporate Services and Audit Branches within the OAG as well as effective Committees to support the OAG in meeting its deliverables. This objective also aims to put in place effective financial management measures and effective monitoring of the OAG’s Strategic Plan and Work Plan deliverables.
Find out more about
- Details
- Written by: Administrator
- Category: About the OAG
- Hits: 41
The Office of the Auditor General (OAG) has five (5) Branches that support the Auditor General in carrying out his duties as mandated by the Solomon Islands Constitution and the Public Finance and Audit Act (Cap 120).
The duties of these Branches range from human resource and asset management to audits and the formulation of policy and strategic planning. These Branches are:
Government Financial Audit (GFAB)
Corporate Governance Financial Audit (CGFAB)